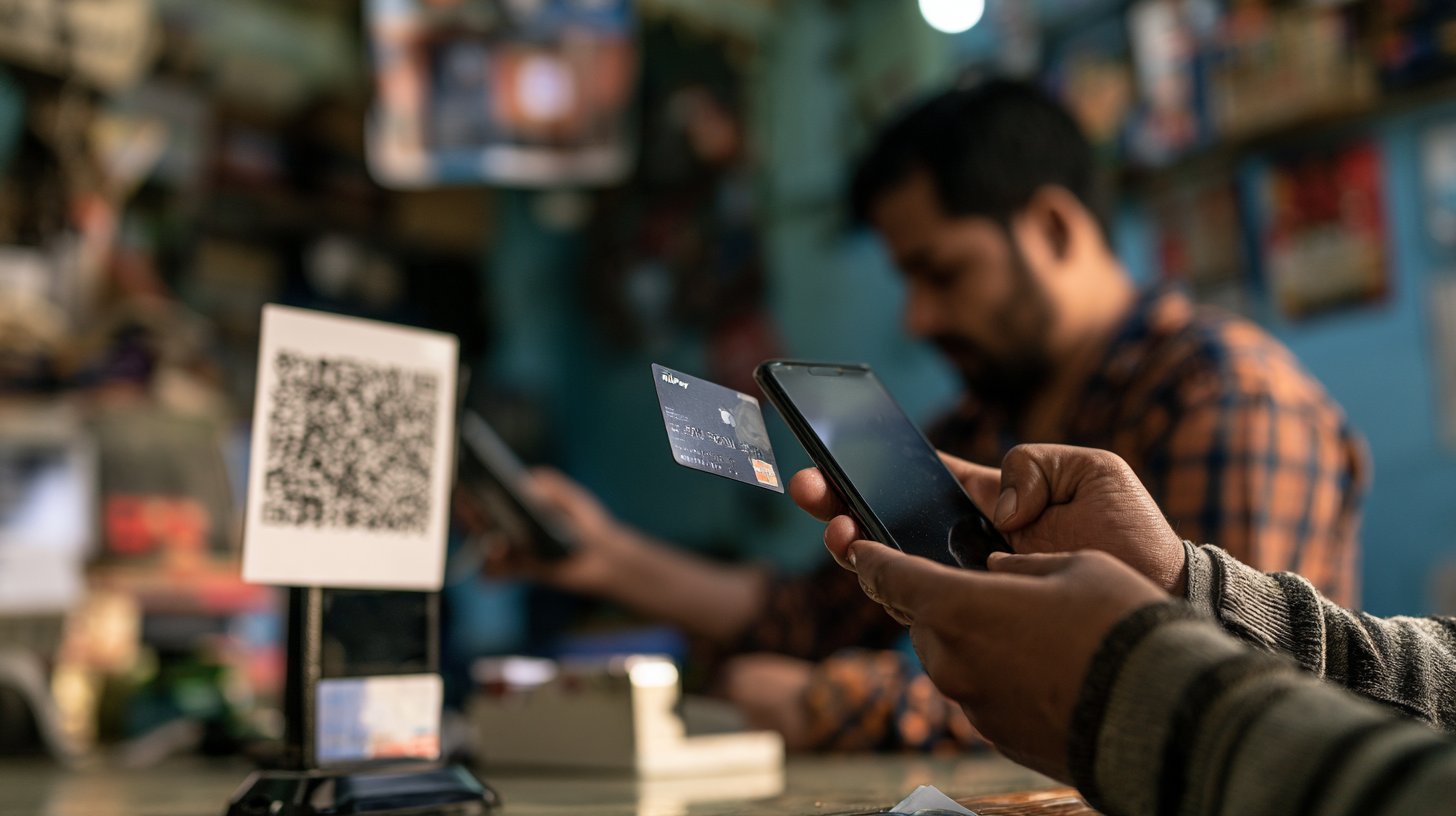
A supported RuPay credit card can fund eligible UPI merchant payments. The amount becomes card borrowing rather than an immediate debit from your savings account. That is a change in how you pay—not free money, guaranteed cashback or permission to spend beyond your repayment budget.
Check eligibility before linking
Confirm the card network, issuer support, registered mobile number and the UPI app’s current eligibility list. NPCI’s product guide describes linking supported RuPay credit cards and paying eligible merchants. It excludes person-to-person transfers, cash withdrawal and other restricted categories. A QR that accepts a bank-account payment does not necessarily accept a credit-funded one.
Do not apply for a new card solely because a merchant displays a UPI sign. If you already have an eligible card, first read its current fees, reward terms and repayment conditions.
Link and make a small planned payment
- Open your existing UPI app from its official installation and find its supported credit-card linking option.
- Select the issuer and follow the verification steps shown for your card. Keep PINs and OTPs private.
- At an eligible merchant, confirm the name and amount, then deliberately choose the credit card as the payment source.
- Check the payment result and the entry in your card account. Save the reference.
Menu labels differ by app and version. If the card is not listed, check issuer support and the registered number rather than repeatedly trying unrelated card details. Keep a bank-account or other payment option for unsupported merchants.
Rewards and fees belong to the specific card
SBI Card’s UPI FAQ, for example, ties rewards to the card product’s exclusions. It also says fuel surcharge reversal does not apply to SBI RuPay UPI transactions. That illustrates why “normal card rewards on every UPI spend” is an unreliable promise.
Compare these items in your own card’s terms:
- Which UPI merchant categories earn rewards and which are excluded.
- The reward rate, billing-cycle cap, redemption value and expiry.
- Annual fees, waiver conditions, surcharges and applicable taxes.
- Interest, late-payment charges and any EMI conversion costs.
Illustrative calculation: an eligible ₹1,000 purchase at a hypothetical 1% reward rate produces ₹10 before caps and exclusions. It is not a reason to buy something unnecessary, and it says nothing about the actual rate on your card.
Understand the interest-free period
Check both the statement date and payment due date. An interest-free period is conditional, not a fixed number of free days after every purchase. For instance, SBI Card’s agreement links that treatment to paying the previous statement’s outstanding balance in full by its due date; carrying a balance can change how new purchases are charged.
Paying only the minimum due is not the same as repaying the full bill. SBI’s statement FAQ explains that minimum-only repayment can stretch debt over years with interest. Read your own issuer’s agreement rather than assuming an example from another card applies.
If you cannot confidently repay the planned purchase, skip the credit-funded option. A rewards calculation should never ignore financing costs.
Limits and failed payments
The NPCI limit circular distinguishes the issuer’s card limit, its credit-on-UPI risk limit and the customer’s chosen control. Available credit and other applicable restrictions still matter; your printed credit limit is not a promise that one UPI payment of that amount will pass.
If a payment fails, check its status and your card account before retrying. For a merchant return, retain the refund reference and ask the issuer how the credit affects the amount due. Do not deduct an expected refund from the bill on your own without checking the issuer’s instructions.
A repayment routine that does not depend on memory
Review small purchases weekly, then reconcile the statement. If you use an automatic bill-payment instruction, verify whether it pays the total or minimum due, whether its cap covers the bill and whether collection actually succeeded. Set a separate due-date reminder as a check.
Use the UPI overview to distinguish bank-account, recurring and international payments. This guide does not rank cards or promise a credit-score improvement from using one.
Reviewed on 27 October 2026. Issuer examples explain why terms differ; they are not a recommendation to borrow or apply for a card.

Techleez Editorial Team
The Techleez publishes practical digital guides. For our scope, use of AI assistance and corrections process, read our editorial policy.
More from this author →